Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Oxley Holdings Limited has announced a re-tap of its existing OHLSP 6.900% 08Jul2024 Corp (SGD), which is expected to launch on 23 September 2021.
Concurrently, noteholders of the OHLSP 5.700% 31Jan2022 Corp (SGD) are invited to tender their holdings ahead of its maturity in January 2022.
Noteholders who tender their 2022 bonds and plan to subscribe to the 6.9% 2024’s re-tap will have priority in the allocation of the new 2024’s.
We have a positive credit outlook on Oxley and would recommend investors to subscribe to the proposed new 2024 issue.
Oxley Holdings Limited (“Oxley”) is optimizing its debt structure and plans to reduce its outstanding short-term indebtedness. The company has announced a tender offer exercise so that bondholders of the OHLSP 5.700% 31Jan2022 Corp (SGD) may sell back their holdings to Oxley MTN Pte. Ltd. (the issuer).
About the tender offer exercise
According to the company’s announcement, the deadline for the tender offer is 22 September 2021, 12pm. The issuer will buy back the notes at 100. Any accrued and unpaid interest from the last interest payment date prior to the settlement date to (but excluding) the settlement date will also be paid. Oxley has not decided on the amount of 2022 bonds that will be bought back as the final acceptance amount will be dependent on the results of the tender offer exercise.
The dealer managers for this tender are Credit Suisse (Singapore) Limited, DBS Bank Ltd. and The Hongkong and Shanghai Banking Corporation Limited, Singapore branch. Bondholders who have invested in the OHLSP 5.7% 2022’s may contact the dealer managers for further information in respect to this tender exercise (Table 1).
Figure 1: Contact details
|
CREDIT SUISSE (SINGAPORE) LIMITED |
DBS BANK LTD. |
THE HONGKONG AND SHANGHAI BANKING CORPORATION LIMITED, SINGAPORE BRANCH |
|
1 Raffles Link #03/#04-01 South Lobby Singapore 039393 |
12 Marina Boulevard, Level 42 Marina Bay Financial Centre Tower 3 Singapore 018982 |
10 Marina Boulevard Marina Bay Financial Centre Tower 2 #45-01 Singapore 018983 |
|
Email: list.piltender@creditsuisse. com |
Email: liabilitymanagement@dbs.com |
Email: hsbcdcmsg@hsbc.com.sg |
|
Attention: Debt Capital Markets |
Attention: T&M – Fixed Income Origination |
Attention: Debt Capital Markets/Transaction Management c/o HSBC Mailroom |
|
Telephone: +65 6212 2000 |
Telephone: +65 6878 9821 |
Telephone: +65 6658 8900 |
| Source: Company announcement dated 8 September 2021 | ||
About the proposed re-opening of the OHLSP 6.9% 2024’s
Oxley intends to re-open the OHLSP 6.9% 2024’s for new subscriptions on 23 September 2021. The bonds will pay a coupon of 6.9% and mature on 8 July 2024. New bond proceeds will be used to finance the purchase of the OHLSP 5.700% 31Jan2022 Corp (SGD), refinancing existing indebtedness, financial requirements and other general corporate working capital. Investors who tendered their 2022 bonds and wish to subscribe to the new 2024’s will receive priority in the allocation of the new medium term notes. The joint book runners for the potential bond re-tap are also Credit Suisse, DBS and HSBC.
Financial and credit highlights
Group revenue increased 58% YoY for the six-month period ended 30 June 2021 (“2HFY2021”). This was broadly due to increasing property prices, favourable lease rates and generally improving global economic conditions. The group made more revenue from their projects in Cambodia, Singapore and Ireland, which was in part, offset by lower revenue from the Royal Wharf project in the UK.
Total profit swung from a loss of SGD 288.0m in 2HFY2020 to a SGD 9.5m gain in 2HFY2021. This was partially because of a SGD 232.3m drop in other losses, which are related to foreseeable losses based on management’s estimates. During 2HFY2021, other losses are mostly made up of provisions, fair value losses, rental support costs and charges for settlement of disputes.
Oxley generated SGD 623.6m of net cash flows from operating activities in FY2021, up from SGD 38.9m in FY2020. We estimate that net cash flows from operating activities increased from ~SGD 125.9m in 2HFY2020 to ~SGD 355.5m in 2HFY2021. Cash and cash equivalents dropped from SGD 384.7m in 2HFY2020 to SGD 215.8m in 2HFY2021. Out of the SGD 215.8m cash position as at 30 June 2021, SGD 42.4m are cash restricted in use, leaving just SGD 173.4m of unrestricted cash.
As mentioned in our earlier article this month – “Buy this SGD bond if you think property prices will keep going up”, Oxley has a weak liquidity profile. However, we believe that the group will have continued access to various funding sources including banks and debt capital markets, and use other liquidity sources to meet current financial obligations.
In our projections, to meet its current financial obligations, we assume Oxley may (i) drawdown on its cash position (SGD 215.8m), (ii) sell its land (SGD 100m), (iii) use the proceeds from the issuance and re-tap of the OHLSP 6.9% 2024’s, (iv) pay down the project debt using project cashflows (SGD 139m), (v) refinance its investment property loan (SGD 97m) and (vi) pay off the remaining SGD 150m of corporate debt using proceeds from the completion of overseas development projects.
The recent rise of coronavirus cases in the dormitories may be a concern but we are not aware of any major stoppage in the completion of its development projects. Construction is still ongoing as it is regarded as an essential activity in most of the economies that the company operates. In Singapore, once a Covid-19 case is detected, a safety time-out or stop work order will be issued. The builder is required to disinfect the affected worksite before resuming construction activity.
Relative valuation
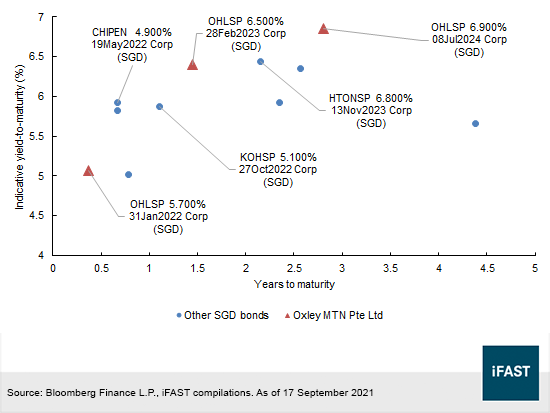
We still hold a positive credit outlook on Oxley and would recommend investors to subscribe to the new OHLSP 6.9% 2024’s. The bond has a yield-to-maturity (“YTM”) of 6.85% on 17 September 2021. It has an attractive valuation given that it is currently the highest yielding SGD note among bonds maturing in three years (Figure 1). However, it is clear that the 2024 bonds are not the most attractively priced along the OHLSP curve as the OHLSP 6.5% 2023’s trade at an indicative YTM of 6.41% and has a shorter maturity.
Figure 1: Relative valuation using bond yields
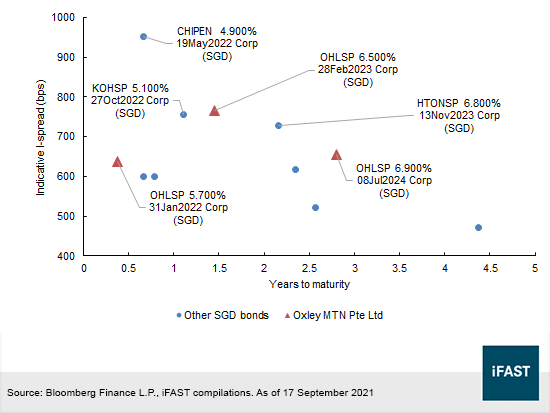
This attractiveness of the OHLSP 6.5% 2023’s can also be seen in the relative valuation chart in Figure 2, where we compare the credit spreads of the same bonds across their maturities. As seen in the chart, the OHLSP 6.5% 2023’s have an I-spread, or credit spread of 766 basis points (“bps”) over the prevailing SGD swap rate, and this exceeds the I-spread of 655bps for the OHLSP 6.9% 2024’s.
On a separate note, while it appears that there may be other bonds with higher credit spreads and shorter maturities such as the CHIPEN 4.900% 19May2022 Corp (SGD), KOHSP 5.100% 27Oct2022 Corp (SGD) or the HTONSP 6.800% 13Nov2023 Corp (SGD), there is currently no liquidity for these notes. Regardless, for information on CHIPEN, KOHSP or HTONSP, investors may refer to the articles “Chip Eng Seng bonds offer attractive yields of around 6%”; “Koh Brothers: Tripped by circuit breaker, but not out” and “Heeton Holdings: To exchange or not to exchange?” respectively.
Figure 2: Relative valuation using credit spreads
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OHLSP 6.900% 08Jul2024 Corp (SGD) and CHIPEN 6.000% 15Mar2022 Corp (SGD). The analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!